
For millions of Ugandans, the nearest bank branch has always been just far enough away to be inconvenient, sometimes impossibly so. A boda rider in a trading town, a smallholder farmer three valleys from the city, a market vendor who cannot afford to lose a day’s income commuting to deposit cash, these are the people formal banking has historically struggled to reach. Pride Bank wants to change that math, and it has just made a move significant enough to notice.
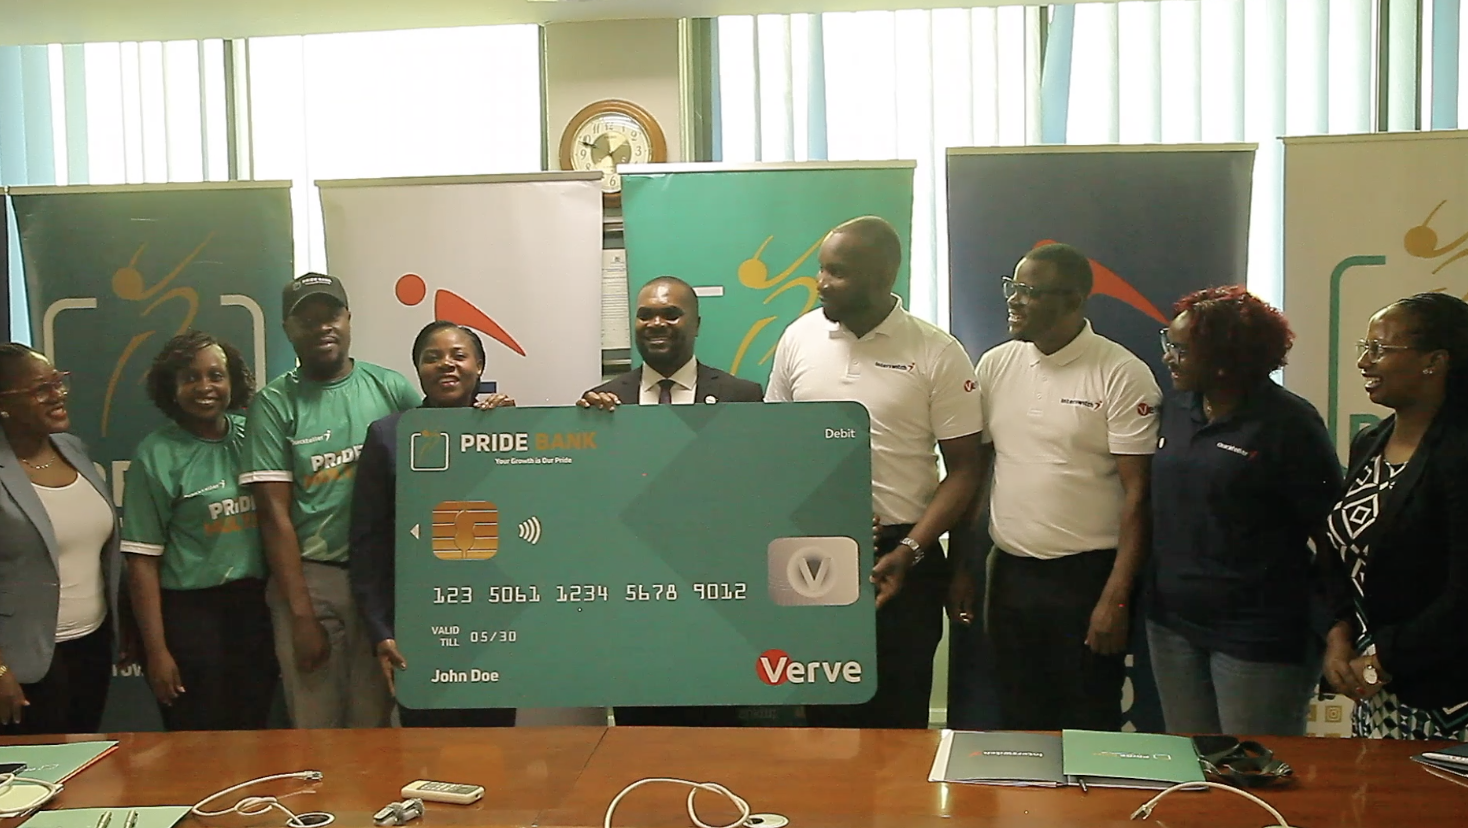
The bank has entered a partnership with Interswitch to extend its distribution network well beyond its physical branch footprint, connecting customers to a web of digital payment channels that effectively brings financial services to where people already are, rather than expecting people to travel to where services sit.
What the Deal Actually Means on the Ground
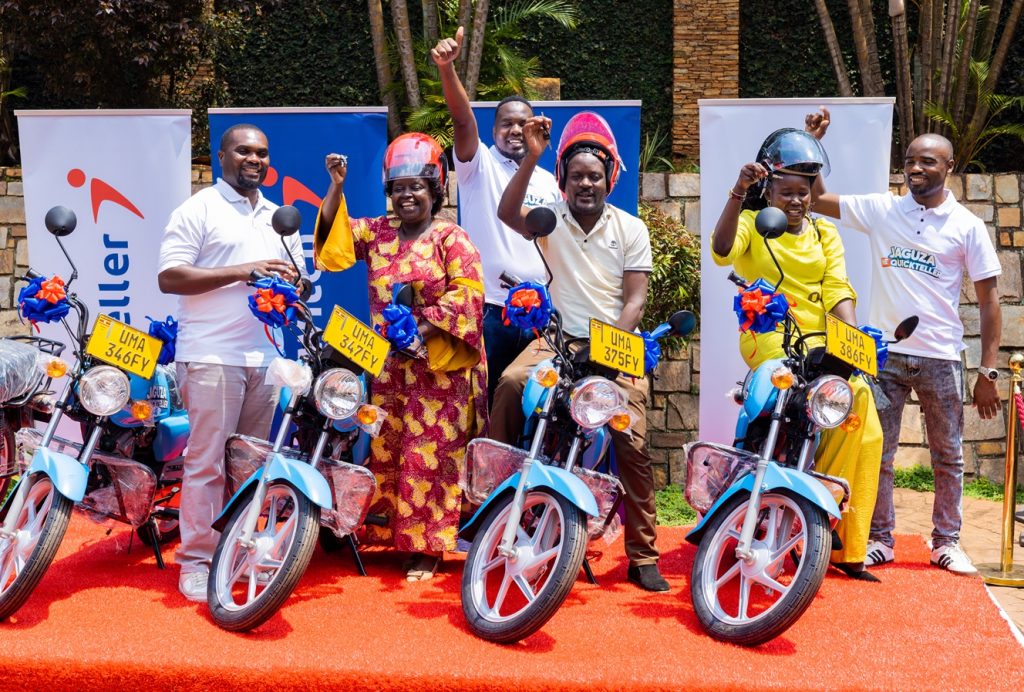
The numbers tell a clear story. Through this arrangement, Pride Bank customers can now access 21,000 Quickteller agents spread across the country. That kind of reach is not something any bank builds with bricks and mortar in a reasonable timeframe. Interswitch, which operates one of Africa’s most established payment infrastructure networks, brings that scale instantly.
Beyond the agent network, the partnership introduces Verve card access, giving Pride Bank customers a route into 650 ATMs and 20,000 payment points. For someone living outside a major urban centre, having a card that works at a nearby payment point is not a luxury, it is the difference between participating in the formal economy and being excluded from it entirely.
Quickteller, Interswitch’s consumer payments brand, has built its reputation on exactly this kind of last-mile reach. Its agent model allows individuals and small businesses to serve as banking touchpoints, essentially functioning as human ATMs and deposit counters in communities where infrastructure is thin but mobile phones and entrepreneurial hustle are not.
Who This Is Actually For
Pride Bank has been specific about its target audience, and that specificity matters. Traders, farmers, boda riders, and students are not an afterthought here, they are the stated focus. These are people whose financial lives move in cash, whose hours do not align neatly with bank opening times, and whose needs for quick, reliable, low-friction transactions are arguably greater than those of the salaried urban professional with a smartphone and a stable wi-fi connection.
Uganda’s informal economy is enormous. The vast majority of economic activity happens outside the structured corporate sector, in markets, on motorcycles, on farms, and in small workshops. Any bank serious about growth in this country has to reckon with that reality. Chasing the small slice of the population already well-served by existing financial infrastructure is a shrinking opportunity. Building for the broad base is where the next wave of banking growth will come from.
The Agent Banking Model Is Proving Its Worth
Agent banking is not a new idea, but its execution is maturing fast across East Africa. Kenya’s M-Pesa ecosystem showed the continent what was possible when financial access is decoupled from physical infrastructure. Uganda has been on a similar, if slower, trajectory, with mobile money networks already transforming how ordinary people handle cash.
What Pride Bank’s Interswitch tie-up adds is a formal banking layer on top of that accessibility. Quickteller agents can handle transactions that go beyond simple mobile money transfers, and Verve cards plug customers into a broader payments ecosystem. For a bank looking to deepen its relevance outside major cities, this combination of agent reach and card-based access is a sensible architecture.
Digital Expansion as a Competitive Necessity
Uganda’s banking sector is not standing still. Telecom-led financial services have already claimed enormous ground among unbanked and underbanked populations. For traditional banks, the pressure to deliver comparable convenience without losing the trust and product depth that formal banking offers is real and growing.
Pride Bank’s move with Interswitch reads as both a defensive and offensive play. Defensive because staying relevant means meeting customers where they are. Offensive because a bank that successfully serves traders, farmers, and students at scale acquires a customer base with deep loyalty and genuine growth potential as those customers’ financial needs become more complex over time.
The 20,000 payment points enabled by Verve cards also open a merchant acceptance angle. When customers know their card works at thousands of locations, card usage behaviour changes. That generates transaction data, which in turn enables better credit decisions and more tailored product offerings, a virtuous cycle that banks everywhere are working hard to build.
Zooming Out: What This Signals for Ugandan Banking
Partnerships like this one between Pride Bank and Interswitch are becoming a template. Banks are increasingly recognising that owning every piece of the customer journey is neither efficient nor necessary. Working with established payment infrastructure players to plug into ready-made networks is faster, cheaper, and more scalable than building from scratch.
For customers, the winner is obvious. More access points, more ways to pay, more places to deposit and withdraw, all without waiting for a branch to be built nearby. For the broader economy, wider financial inclusion tends to correlate with higher savings rates, better credit access, and stronger small business formation.
Uganda still has significant ground to cover on financial inclusion. But moves like this one suggest the gap between aspiration and reality is narrowing, one Quickteller agent at a time.
The question worth sitting with is this: as banks race to extend their digital reach into every corner of the country, are the products and services on offer genuinely designed for the farmers, traders, and boda riders being targeted, or is the infrastructure expanding faster than the thinking about what these customers actually need?